You Were Paid Yesterday. What Happened?
Why does your salary disappear so quickly? Explore the everyday spending habits, financial pressures, and small expenses that can turn ₦150,000 into a mid-month money crisis.
Loading...
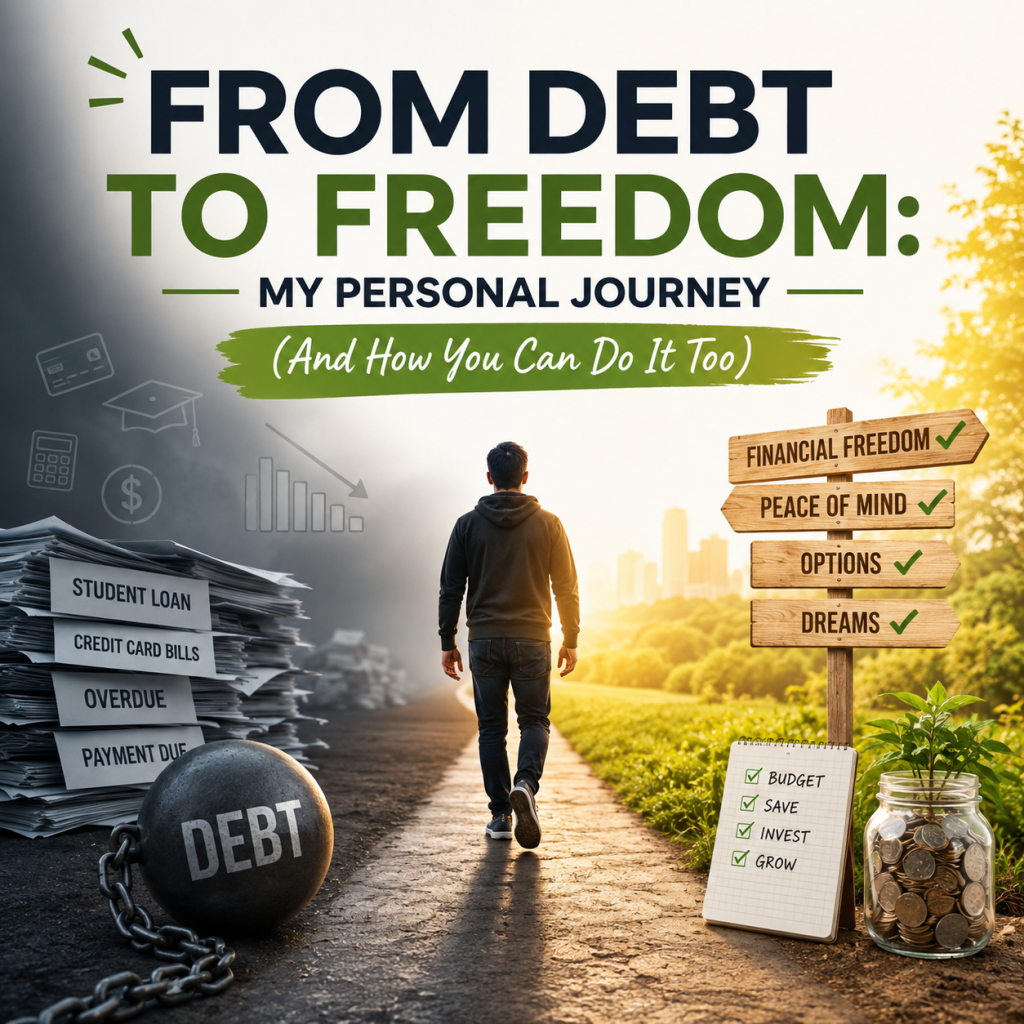
Discover my personal journey from student loan debt to financial freedom, including the struggles, lessons, and practical steps that helped me take control of my finances and how you can do the same.
I still remember the first time I saw the debit alert. One notification was all it took to change the mood of my day.
Student Loan Payment: -₦45,000.
And trust me, it isn’t even the money that gets to you. It’s that notification sound from your bank or loan app that tightens your chest because you’re already wondering what it says. The loan was supposed to help you get ahead, yet some days it feels like your life is planned around paying it back.
You will almost swear that your supposed village people are after your life.
I remember sitting at my kitchen table at 2 a.m., spreadsheet open, staring at a number that seemed to grow larger every time I blinked. I was paying the minimum, doing exactly what I was told, and yet, the balance barely budged. It felt like running on a treadmill set to a speed I couldn’t match, no matter how hard I pushed. If you’re reading this, and somehow found in this past shoes of mine wondering if you’re stuck forever, please you’re not. Let that sink deep in you.
(Perfection is not key)
The first thing I had to unlearn was the idea that I needed to be perfect to fix this. I thought I needed to save every naira, cut out every cup of zobo or suya at the weekend, and live like a monk, but that kind of perfectionism is a trap that leads to burnout.
When I finally sat down to make a plan, I found two main ways to fight back. One was mathematically perfect, the other was emotionally necessary, and honestly, you need to pick the one that keeps you moving. The first is the Avalanche, the smart way where you list your loans by interest rate from highest to lowest and throw every extra naira at the loan with the highest rate to save the most money in the long run. It’s the most efficient path, but it’s boring. If your highest-interest loan is also your biggest one, you could be hitting it for five years without seeing a single loan disappear, working hard but not getting to cross anything off your list, which makes it easy to lose motivation.
Then there’s the Snowball, the way I chose, where you list your loans by balance from smallest to largest, ignore the interest rates, and just attack the smallest one first because you need a win. I didn’t care much about the math but more about getting something off my plate, and once that small loan was gone, I had more money to throw at the next one, and the next, and the next. It took me longer than the Avalanche method would have, sure, but I stuck with it
While you’re figuring out your strategy, don’t forget the government’s secret weapon if you have federal loans because you are sitting on a goldmine that most people don’t even know exists. For the first month, I was on the standard 6-month plan, paying my minimum and thinking that was it, until I found out about the SAVE Plan.
I put myself on the SAVE plan and as time went on, my payment dropped from ₦45,000 to ₦12,000. You have to do the work though, recertifying your income every month and checking the form because if you forget, the system kicks you back to the standard plan and your payment jumps up, which is a trap, but if you stay on top of it, it’s a lifeline.( Unfortunately that plan doesn’t seem to exist anymore )
And you need to find the money without losing your mind because everyone tells you to "cut out your coffee," but please, a ₦2,000 cup of coffee isn’t going to pay off a ₦3,000,000 loan; it’s insulting advice. You don’t have to make yourself miserable to pay it off faster. When extra money comes your way, whether it’s a tax refund, a bonus, or even a salary increase, consider putting some or all of it toward your loan before you find somewhere else to spend it.
And then there’s housing. If you can spend less on where you live for a while, that extra money can make a real difference. But life isn’t always that simple. Sharing a place sounds great until you end up with a roommate who turns your peace of mind into a daily struggle. Also, moving back home isn’t an option for everyone either. Sometimes the cheaper choice comes with a price you don’t see on paper.
If you have an arrangement that works for you, don’t take it for granted. And if you don’t, don’t be too hard on yourself. The goal isn’t to make life unbearable just to pay off debt but to find the balance between making progress and protecting your sanity. To be honest, there will be days when you look at the balance and wonder if you’ll ever finish paying it off. It can feel discouraging, and you might even think about giving up and just paying the minimum every month.
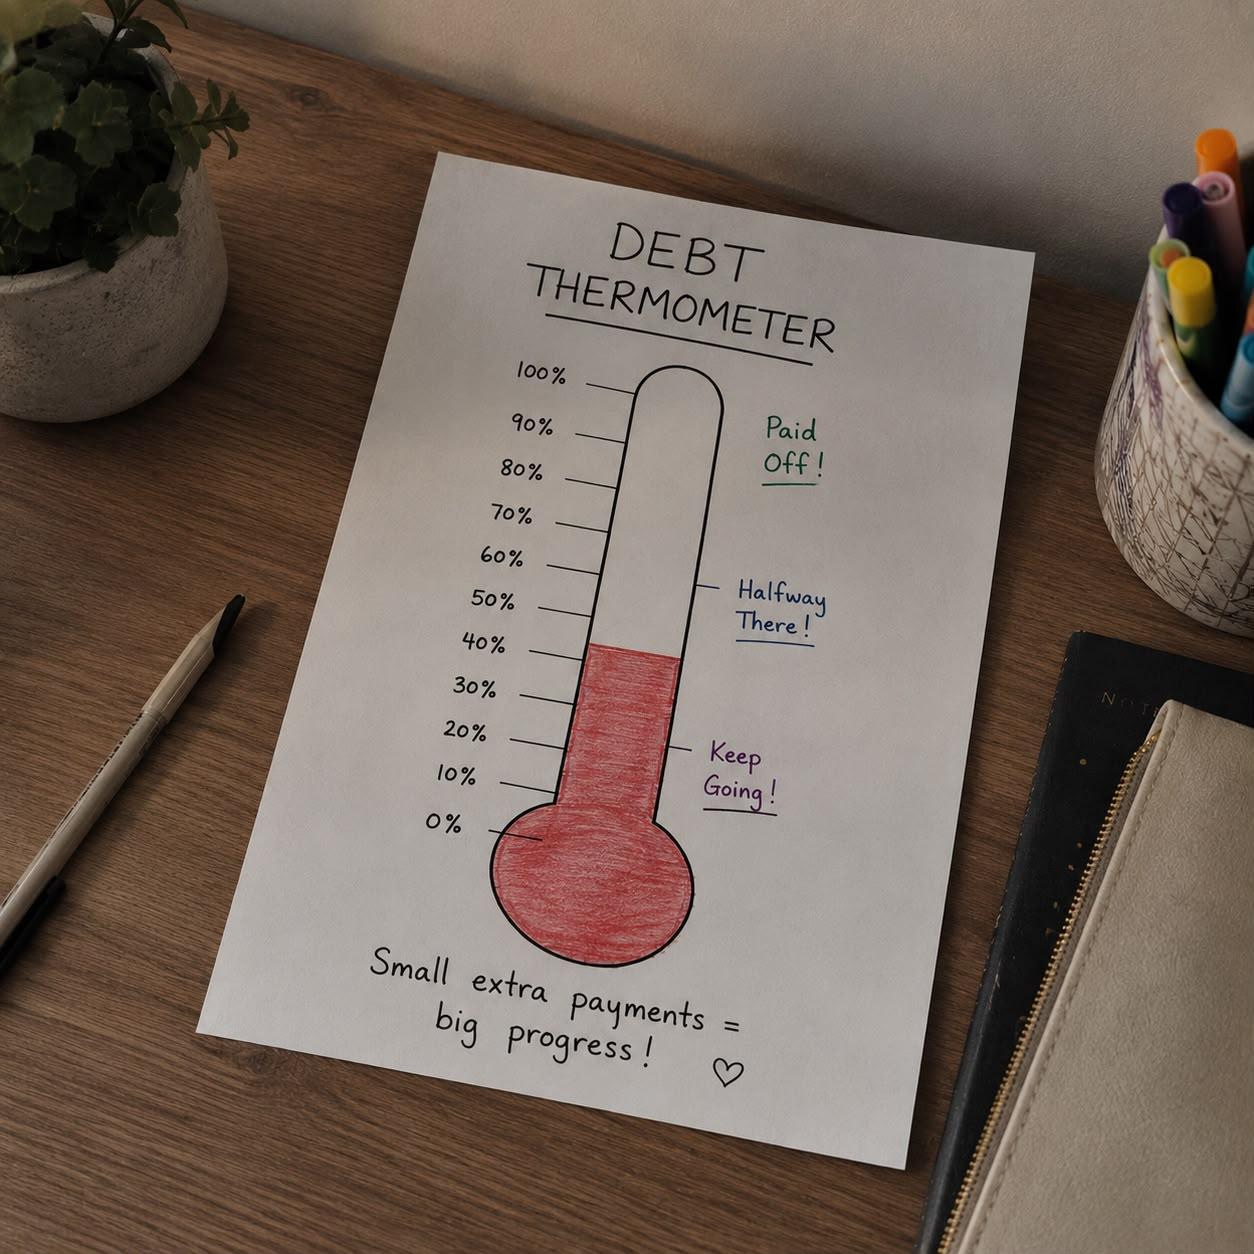
When I felt that way, I reminded myself that this wouldn’t last forever. I also found little ways to stay motivated. I drew a simple “debt thermometer” on a sheet of paper and coloured it in every time I made an extra payment. Watching that progress grow kept me going. And I celebrated the small wins. When I paid off my first 3-month loan, I didn’t rush to buy something expensive. I just treated myself to a really nice meal, and took a moment to be proud of how far I’d come.
You have to treat yourself like a human being, not a robot, be kind to yourself when you slip up, and remember that you are fighting a battle that many people are fighting and you are not alone. So, take a deep breath, log in to your account, write down the numbers, pick a strategy (Avalanche or Snowball, it doesn’t matter as long as you pick one), set up an autopay for a little more than the minimum, and then just start. One little tiny step at a time,
*P.S. If you’re feeling stuck, go find a community. Join a good legit finance group on Twitter or Reddit, read the stories, and you’ll see that you are not alone. There are people who have paid off millions. They did it. You can too.
Why does your salary disappear so quickly? Explore the everyday spending habits, financial pressures, and small expenses that can turn ₦150,000 into a mid-month money crisis.
Why do we spend money trying to look successful? Explore the psychology behind lifestyle spending, social pressure, and the hidden cost of looking financially fine.
Learn how credit scores work, why they matter, and practical steps you can take to improve your credit score and make borrowing more affordable.